PRODUCT
Claims processing involves a lot of information, a lot of steps, and usually a lot of manual work. A claim may start with a customer describing what happened, followed by forms, emails, photos, invoices, policy documents, repair estimates, and other supporting information. Someone then has to collect that information, check it, enter it into the right systems, and decide what needs to happen next. This is where AI claims automation can make a practical difference. The goal is not to remove peo


Claims processing involves a lot of information, a lot of steps, and usually a lot of manual work.
A claim may start with a customer describing what happened, followed by forms, emails, photos, invoices, policy documents, repair estimates, and other supporting information. Someone then has to collect that information, check it, enter it into the right systems, and decide what needs to happen next.
This is where AI claims automation can make a practical difference. The goal is not to remove people from the claims process. It is to reduce the amount of repetitive work around the claim, make information easier to process, and help claims teams spend more time on cases that actually need their attention.
AI claims automation uses AI to handle specific tasks within the claims process that would otherwise require manual work.
Depending on the workflow, this can include extracting information from documents, classifying incoming claims, identifying missing information, checking data against predefined rules, summarizing claim information, or routing a claim to the right person or process.
It is important to distinguish this from fully automated claims handling.
In most insurance environments, claims involve decisions, exceptions, regulations, and customer situations that require human judgment. AI is often more useful when it handles the structured and repetitive parts of the process while keeping people involved where they add the most value.
The question is therefore not simply, "How much of the claims process can we automate?" A better question is: "Which parts of the process are repetitive, time-consuming, and structured enough for automation?"
Claims automation can begin before a claims handler ever reviews the case.
The first step is usually the First Notice of Loss (FNOL): the initial report that an incident has occurred.
This information can come through different channels: a phone conversation, online form, email, chat, or another digital workflow.
At this stage, AI can help capture and structure the information being provided.
For example, instead of a claims employee manually reading a long customer description and entering the relevant details into a claims system, an AI system can identify information such as:
The important part is not simply extracting the data. It is turning an unstructured customer interaction into information that can be used by the next step in the claims process.
Insurance claims rarely arrive in one clean format.
A single claim might include a customer statement, a PDF report, several photographs, an invoice, an email, and information already stored in an internal system.
Manual processing becomes difficult when employees have to move between these sources and enter information into different systems.
AI can help by extracting relevant information and turning it into a structured format.
For document-heavy workflows, this may involve identifying specific fields, classifying documents, extracting key values, and connecting information from multiple files.
The result is a more consistent set of claim data that can be passed to the next stage of the workflow.
Once information has been structured, the next question is whether the claim contains what is needed to move forward.
AI can help identify missing or inconsistent information and flag cases that require attention.
For example, a workflow might check whether required documents have been provided or whether certain information is present before a claim moves to the next stage.
This does not necessarily mean that AI makes the claim decision.
Instead, it can perform the checks around the decision and make sure the claims handler has the information needed to make it.
That distinction matters.
In insurance, automation should not be treated as a replacement for every decision. In many cases, its value comes from preparing the case properly before a person needs to make a decision.
Not every claim should follow the same process.
Some cases may be straightforward. Others may involve missing information, unusual circumstances, higher risk, or a situation that requires specialist review.
Claims automation can help classify and route cases based on predefined business rules and the information available.
A straightforward case may continue through a standard workflow.
A case that requires additional review can be flagged and sent to the appropriate team.
This is one of the practical benefits of automated claims processing: employees do not have to manually determine the next step for every incoming case.
The system can handle the predictable paths and surface the cases that need attention.
Automation does not stop once a claim reaches an employee.
AI can also help organize the information around the case so that the claims handler does not have to spend as much time gathering it.
Instead of reviewing several documents and systems to understand what happened, the employee can receive structured claim information, extracted data, relevant documents, and a summary of the case.
This can reduce the amount of administrative work around the claim.
It also gives employees more time to focus on the parts of the case that require experience and judgment.
Claims are also a customer experience process.
Customers want to know whether their claim has been received, whether anything else is needed, and what happens next.
AI-powered customer service can support some of these interactions by providing updates, answering common questions, and helping customers provide missing information.
The important part is that the customer interaction should be connected to the actual claims workflow.
An AI agent that can only answer general questions has limited value. An agent that can access the relevant information, understand where the claim is in the process, and take an appropriate action can be much more useful.
As the claim moves through the workflow, automation can continue to support repetitive tasks.
Depending on the type of claim and the insurer's processes, this could include:
The exact level of automation will depend on the claim type, business rules, systems, and regulatory requirements.
This is why claims automation is better understood as a workflow than as one AI tool.
Different parts of the process can be automated in different ways.
Not every part of claims processing is equally suitable for automation.
A good starting point is usually a process that is:
High volumeThe team handles the same type of task frequently.
RepetitiveThe steps are similar from one case to another.
StructuredThere are clear rules for what information is needed and what should happen next.
Time-consumingEmployees spend a meaningful amount of time on the task.
Easy to measureThe insurer can compare the process before and after automation.
For example, processing incoming claim documents may be a good candidate for automation if employees currently spend significant time opening files, identifying document types, extracting information, and entering it into another system.
A complex coverage decision may be a very different situation.
The goal is not to automate because AI is available. The goal is to automate where it improves the way the work is done.
AI claims automation depends on more than the AI model itself.
The technology needs access to the right information and a clear understanding of what it is allowed to do.
There are several things insurers should consider before automating a claims workflow.
AI needs access to the information required for the task. This may include claims systems, policy information, documents, customer data, or other internal sources.
The system needs to know what should happen in different situations. Business rules, permissions, escalation paths, and exception handling are all part of the workflow.
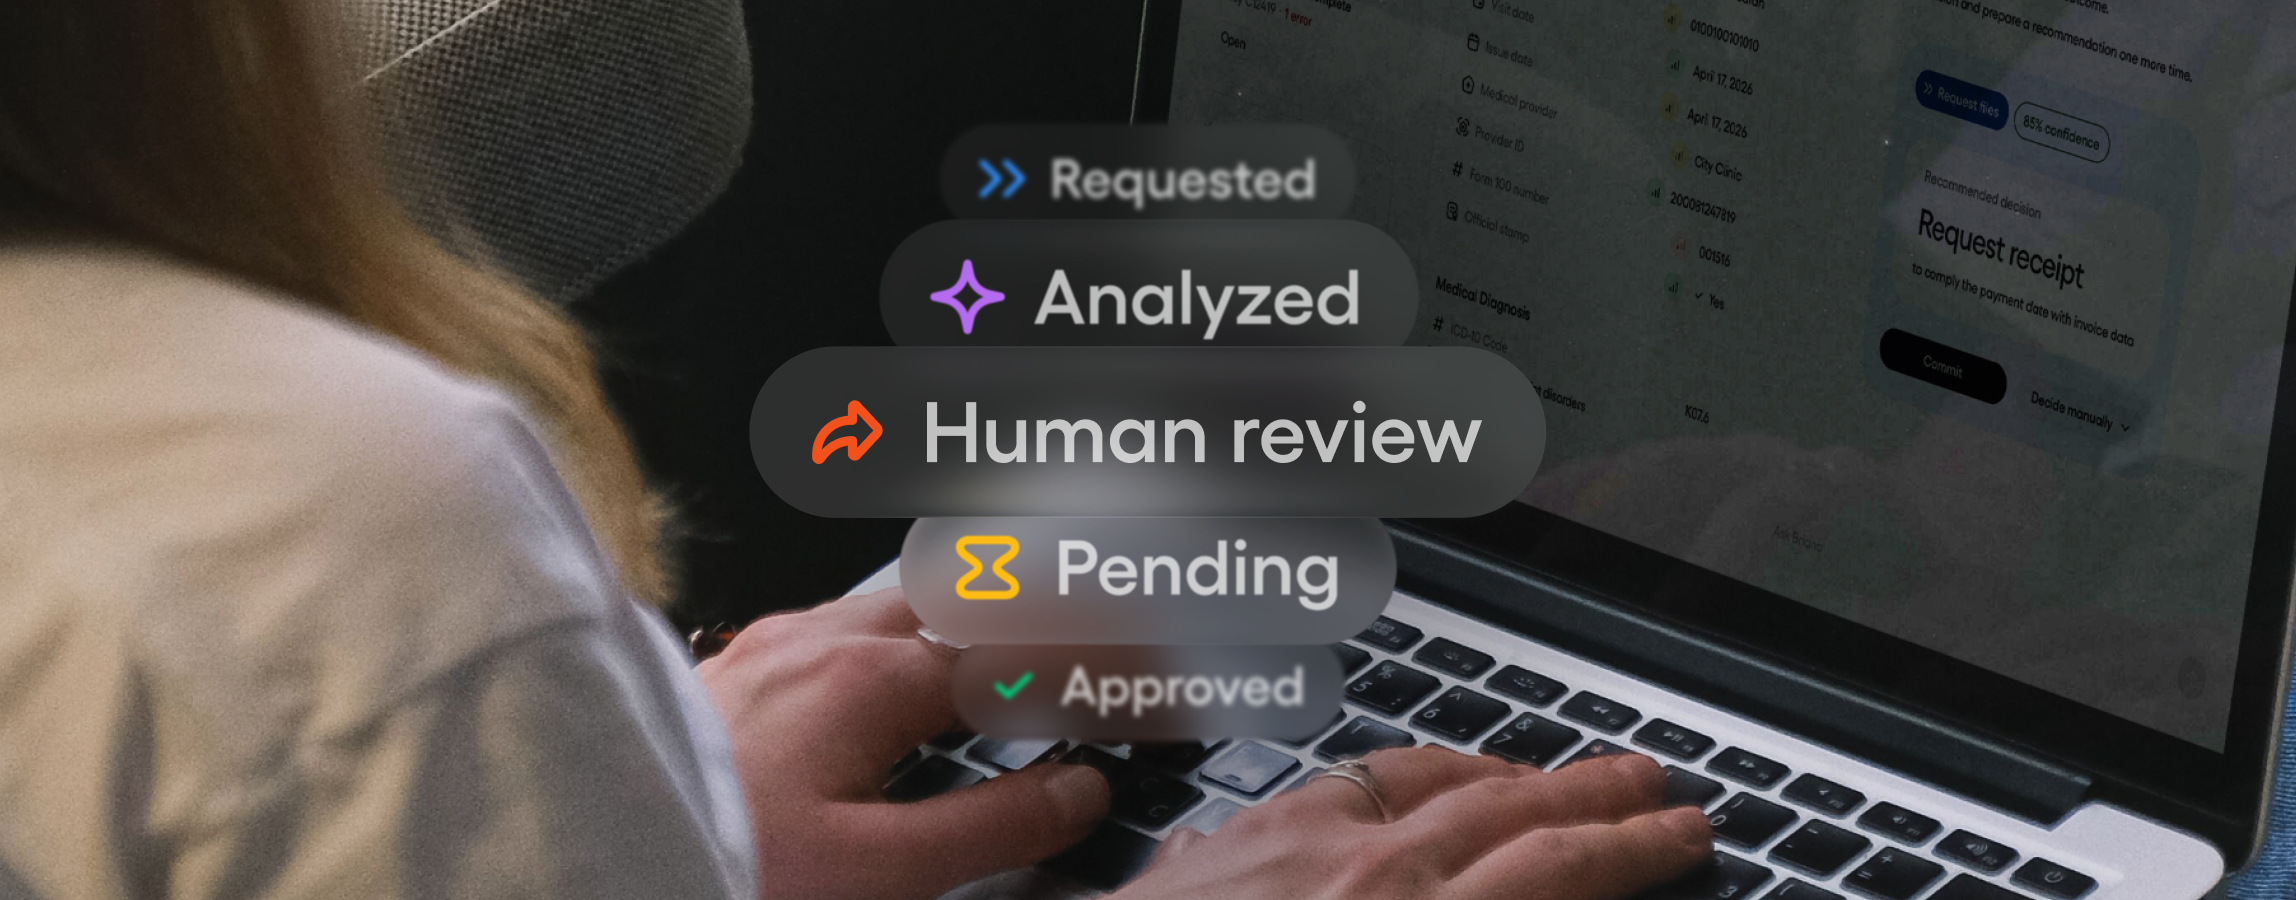
There should be a clear path for cases that fall outside the automated process. Human review is especially important for exceptions and decisions that require judgment.
Claims contain sensitive customer and insurance information. Data handling, access controls, auditability, deployment, and data residency all need to be considered when introducing AI into claims operations.
Automation should be measurable.
Insurers need to know how many cases are being processed automatically, where cases are being escalated, where errors occur, and whether the workflow is actually reducing manual effort.
The impact of automation should be measured against the existing process.
Useful metrics can include:
The right metrics will depend on what is being automated.
For example, if the main problem is document processing, reducing the time employees spend extracting and entering information may be the most relevant measure.
If the problem is customer communication, response and resolution times may matter more.
The point is to establish a baseline before automation so there is something to compare against.
The most useful approach to AI in insurance claims is usually not to replace the entire claims process with AI.
Claims are too varied for that to be a practical starting point.
Instead, insurers can look at the process step by step and identify where automation can remove repetitive work, improve the flow of information, and help employees make better use of their time.
A claim can involve many small tasks between the first customer interaction and final resolution. When those tasks are connected into a well-designed workflow, AI can take on a meaningful part of the operational workload without removing human oversight.
That is where claims automation becomes useful: not as an isolated AI feature, but as part of the way claims work is actually done.